Introduction
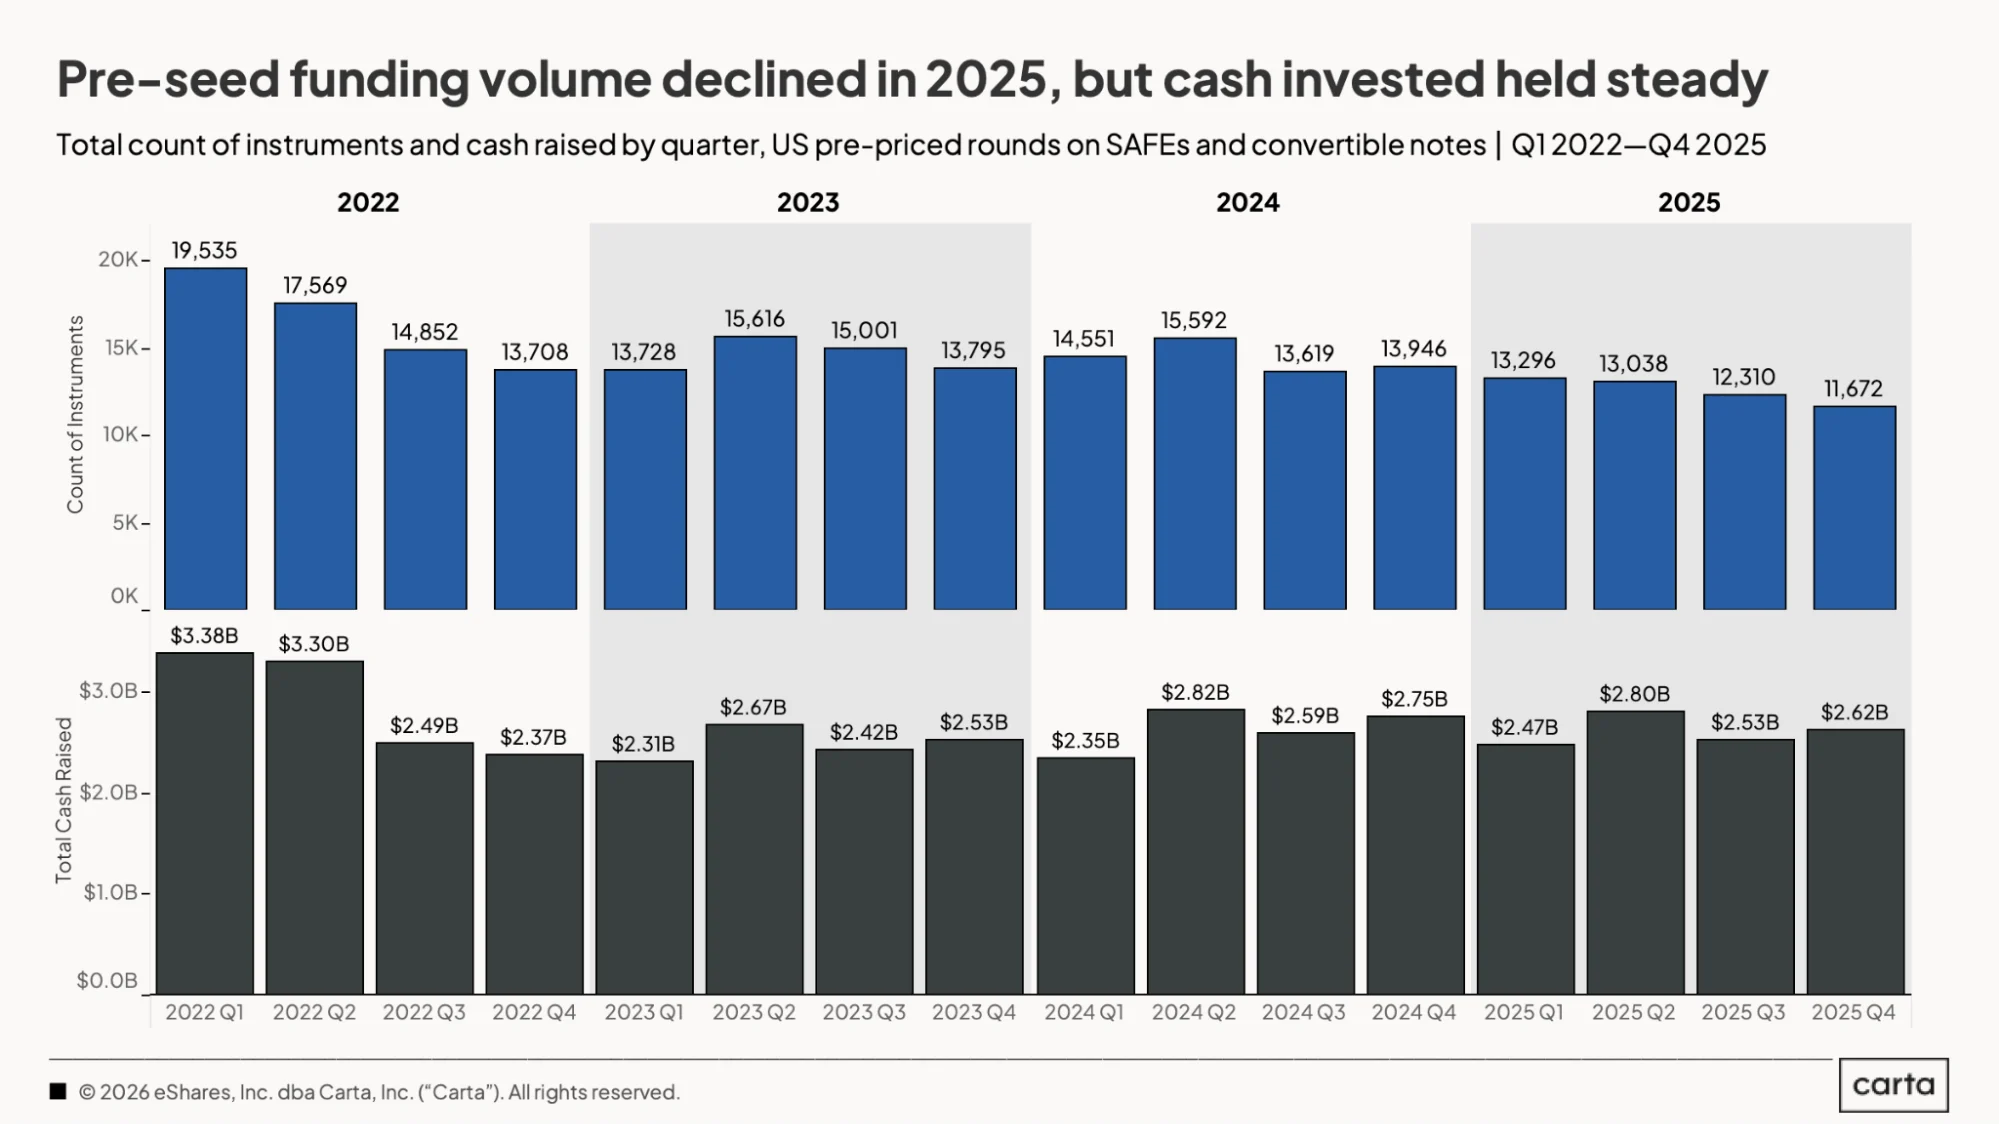
2025’s a wrap, so we crunched the numbers to bring you our definitive breakdown of the year in pre-seed startup funding. Over the course of the full year, U.S.-based startups on Carta raised $10.4 billion across 50,316 SAFEs and convertible notes.
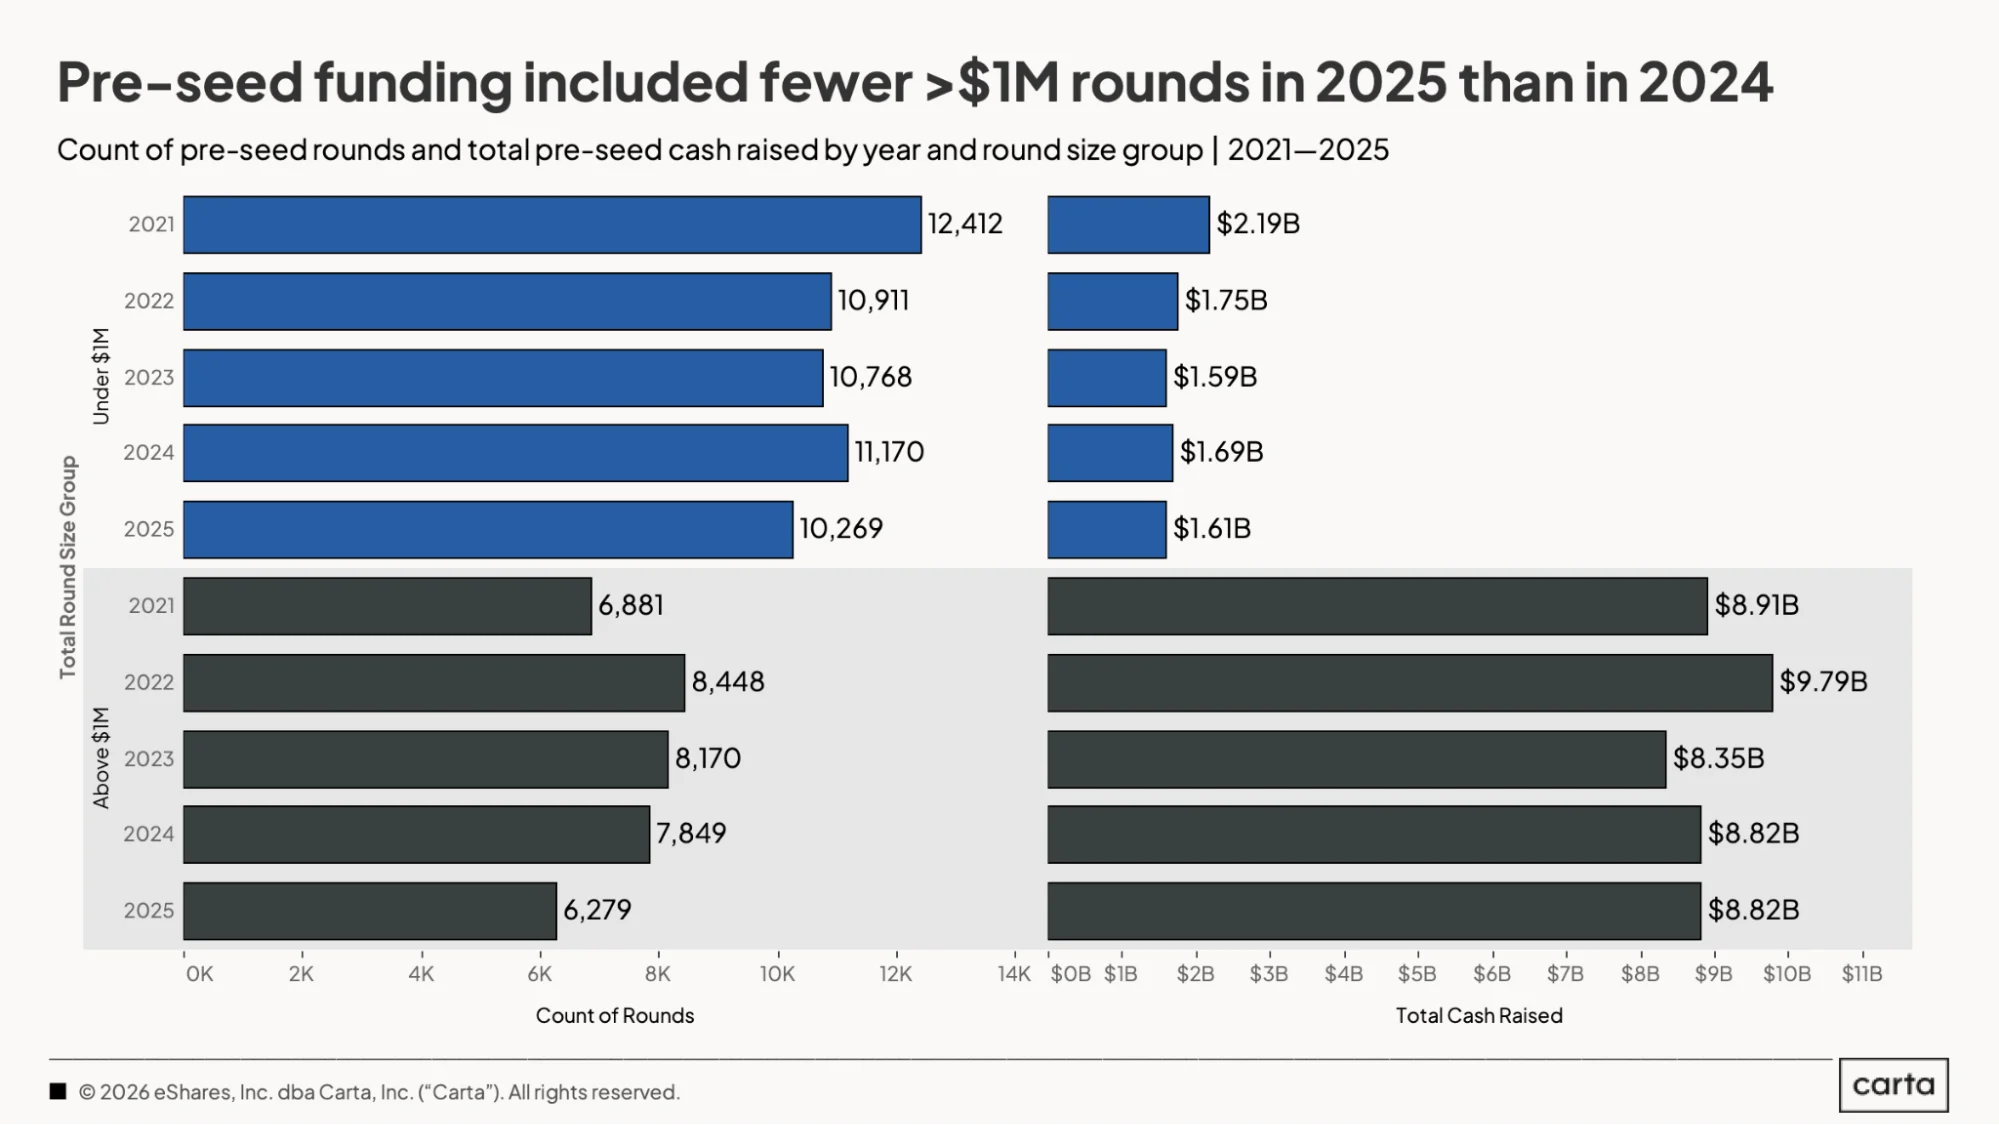
Compared to 2024, that’s a 1% decline in total cash invested—not a significant difference—but a 13% decline in the count of instruments. As we also saw on the priced equity side of fundraising, venture capital grew increasingly concentrated in 2025.
The post-money SAFE with a valuation cap but no discount continues to be the standard pre-seed instrument. In 2025, median val caps on post-money SAFEs hovered around $10 million for rounds in the $250,000 to $1 million range and $15 million for rounds in the $1 million to $2.5 million range.
Continue reading for detailed charts and data on pre-seed investment volume, common deal terms, industry trends, top metro areas, and more.
2025 in review
Concentration of capital: 11,672 SAFEs and convertible notes were issued in Q4 2025, the lowest we’ve seen in recent years. However, those instruments represented $2.62 billion in investments, which is similar to the last several quarters.
The popularity of pre-priced funding: Founders are raising larger sums of money on convertible instruments before switching to priced equity. In 2025, the majority of early-stage rounds under $4 million were completed using SAFEs or convertible notes.
SAFE valuation caps rise: In 2025, val caps on SAFEs increased across deal sizes, while caps on convertible notes experienced greater fluctuation. Also, convertible notes tend to have lower val caps than SAFEs.
Founders building in atoms: While SaaS remains the largest startup industry, hardware and biotech/pharma finished 2025 as the second and third largest by total cash raised. This is a noticeable difference from 2024, when hardware was third and biotech/pharma was fifth.
Key trends