Shares of common stock and preferred stock are the two main types of equity compensation issued by private companies and startups. Generally, shares of common stock are issued to founders and employees, while shares of preferred stock are issued to investors.
To describe a company’s stock, you may come across terms like “issued and outstanding shares,” “fully diluted shares,” or “ total “authorized shares.” These terms refer to different ways to scope the equity in your company.
What are fully diluted shares?
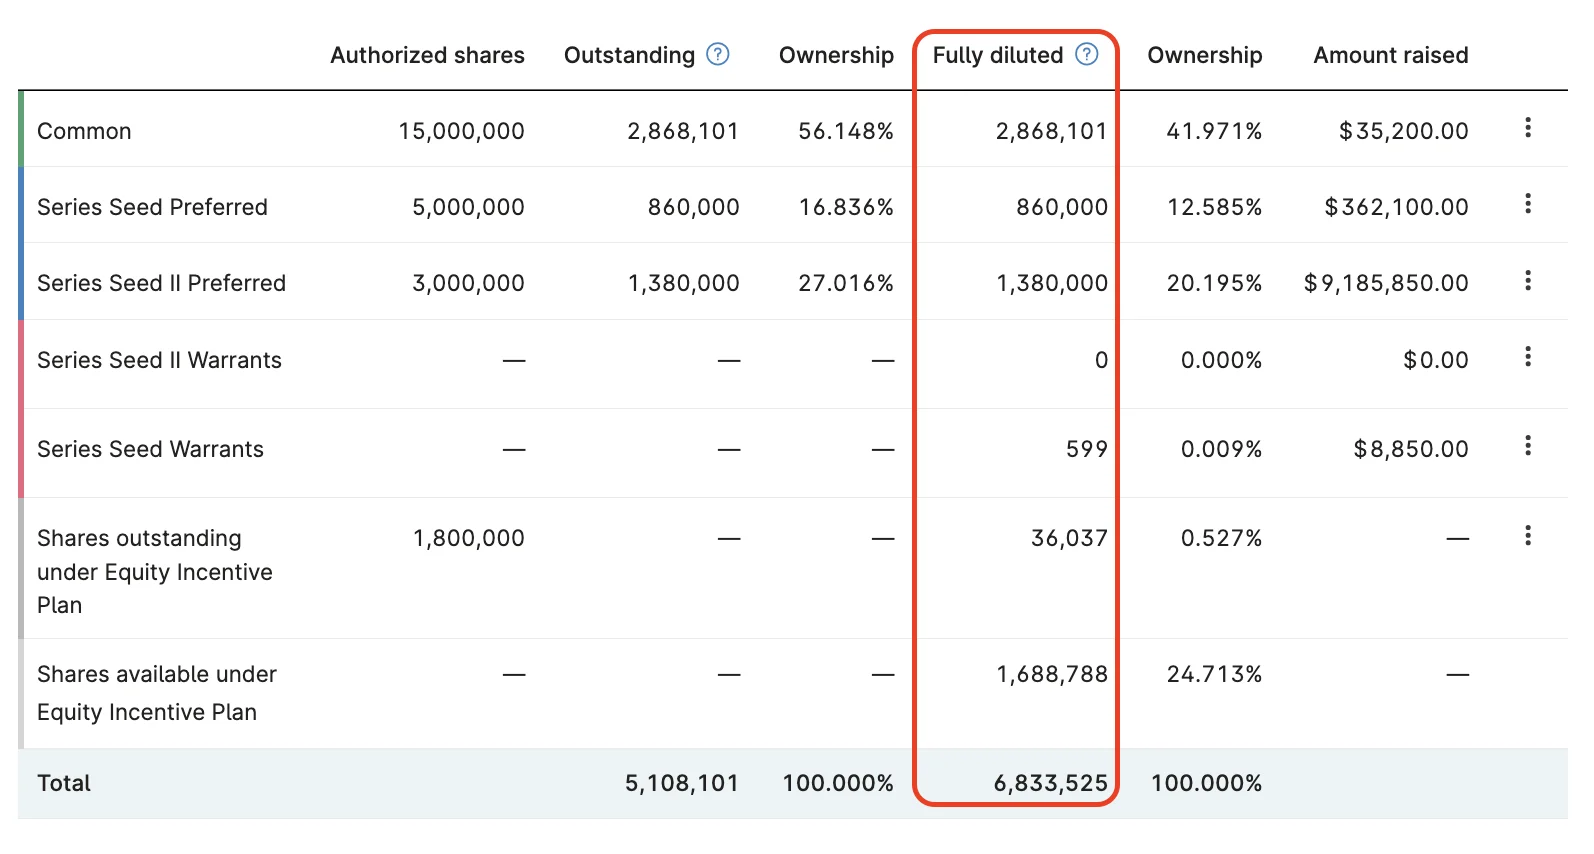
The fully diluted share count is the total common share equivalent (common stock, plus preferred stock calculated as if it was converted into common stock) of all equity that has been issued or is expected to be issued by a company.
A full dilution calculation includes outstanding common shares, preferred stock counted as if converted to common, and potential shares from the exercise of stock options and warrants. It also includes the shares reserved in the company’s option pool.
Fully diluted shares are an important metric to help you understand the value of your equity percentage and to calculate diluted earnings per share. There are several other ways to count equity, including the authorized share count or the number of outstanding shares.
Fully diluted shares vs. authorized shares
The authorized share count is the maximum number of shares a company is legally allowed to issue, outlined by its incorporation documents.
Fully diluted shares vs. outstanding shares
The outstanding share count is the amount of stock that has been issued and is currently held by shareholders. It does not include equity that is not yet converted or exercised into stock, such as warrants, options, restricted stock units (RSU), or stock appreciation rights (SAR).
Typically, only outstanding stock has voting rights, while options, warrants, and other securities that have not yet been exercised or converted do not. (However, this is dependent on each company’s specific incorporation document).
Earnings Per Share
The distinction between outstanding shares and fully diluted shares is important when you are calculating earnings per share, an important metric for understanding the profitability of the company.
Basic earnings per share is the net income of the company divided by outstanding shares, while diluted earnings per share is the net income divided by the fully diluted share count.
How to calculate fully diluted shares
You can calculate your fully diluted share count with the formula below:
Fully Diluted Shares = Common Shares Outstanding + Preferred Stock (as converted to common) + Stock Options + Warrants + Unissued Option Pool Shares
Note on SAFEs and convertible notes: SAFEs and convertible notes are not counted in the fully diluted share count until they convert into shares. Until then, they’re tracked separately. Once a SAFE or note converts (typically at a priced round), the resulting shares are included. To see how unconverted SAFEs and notes would affect ownership, use a pro forma or as-converted view, which models the conversion without changing the actual share count.
If your company uses Carta for equity management, you can view the fully diluted share count when viewing your cap table by share class.
Share dilution and why “fully diluted shares” matter
Share dilution is the decrease in ownership percentage for existing shareholders when a company issues or reserves new shares of stock. Therefore, when an investor, founder, employee, or any other shareholder is trying to understand what percentage of ownership they own in a company, it is usually most accurate to think about that percentage on a fully diluted basis.
For example, let’s say you use the fully diluted share count to calculate how much equity you own in your company. If you determine you own 1% of the company using full dilution, then that ownership percentage won’t change in the future—even as your co-workers exercise their options, or if a new hire is granted equity from the option pool.
Alternatively, if you calculated your ownership percentage based on outstanding shares, such actions would dilute your percentage ownership.
DISCLOSURE: This communication is on behalf of eShares, Inc. dba Carta, Inc. ("Carta"). This communication is for informational purposes only, and contains general information only. Carta is not, by means of this communication, rendering accounting, business, financial, investment, legal, tax, or other professional advice or services. This publication is not a substitute for such professional advice or services nor should it be used as a basis for any decision or action that may affect your business or interests. Before making any decision or taking any action that may affect your business or interests, you should consult a qualified professional advisor. This communication is not intended as a recommendation, offer or solicitation for the purchase or sale of any security. Carta does not assume any liability for reliance on the information provided herein. © 2026 Carta. All rights reserved. Reproduction prohibited.